Monday, May 22, 2024
Global Smartphone Shipments Up 1% in Q1 2026; HDI Substrate Demand Rises
by
Published
Views:
Editor’s Note: On May 18, 2026, Omdia released its latest quarterly market data, revealing a modest but structurally meaningful uptick in global smartphone shipments — with implications for high-density interconnect (HDI) substrate suppliers, particularly those based in China. This development signals renewed momentum in premium device production and tightening supply chain validation for advanced packaging substrates.
Event Overview
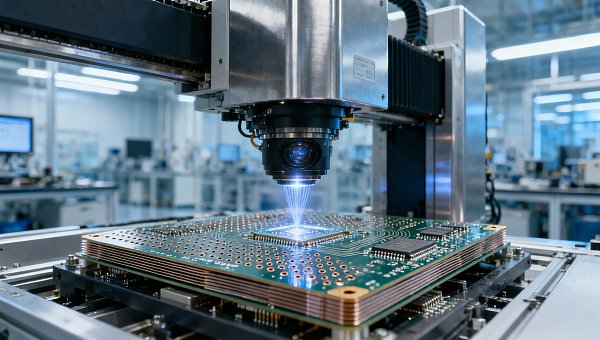
Omdia’s latest data shows global smartphone shipments rose approximately 1% year-on-year in Q1 2026. Domestic Active Components manufacturers confirmed receipt of additional HDI substrate orders from Tier-1 OEMs — including Samsung and Xiaomi — for delivery in Q2–Q3 2026. Lead times have been compressed to under eight weeks. These orders cover HDI substrates with ≥12 layers, microvias ≤50 μm, and embedded capacitor integration capabilities.
Industries Affected
Direct Trading Enterprises
Trading firms specializing in HDI substrate distribution face increased demand visibility and tighter order-to-delivery cycles. The compression of lead times to under eight weeks implies reduced inventory buffer windows and higher working capital requirements — especially for firms acting as intermediaries between Chinese substrate makers and overseas assembly partners.
Raw Material Procurement Enterprises
Suppliers of specialized copper foil, ABF-like dielectric films, and ultra-fine drill bits report rising inquiry volumes from HDI substrate producers. Because the new orders emphasize 12+ layer stacks and ≤50 μm microvias, material yield consistency and traceability (e.g., low-profile copper with <2 μm roughness) are now under closer scrutiny — raising qualification thresholds for upstream vendors.
Manufacturing Enterprises (HDI Substrate Producers)
Active Components manufacturers — particularly those certified for Samsung and Xiaomi HDI specifications — are experiencing elevated capacity utilization. The structural shift toward premium devices means greater emphasis on process control at sub-50 μm drilling, sequential lamination repeatability, and buried passive integration — not just volume scaling. Yield pressure remains high, but customer-driven technical co-development is intensifying.
Supply Chain Service Providers
Logistics and customs compliance services supporting cross-border HDI substrate shipments (especially from China to Vietnam/Korea assembly hubs) are seeing accelerated documentation turnaround demands. With shorter lead times, real-time shipment tracking, bonded warehousing near OEM contract manufacturers, and IPC-4104-compliant certification verification have become operational differentiators.
Key Focus Areas & Recommended Actions
Prioritize Technical Validation Over Volume Quotation
Given that new orders explicitly reference 12L+ stacks and microvia specs, substrate suppliers should allocate engineering resources toward rapid revalidation of existing processes — rather than expanding blanket capacity. Customers are rewarding speed-to-spec compliance, not just cost competitiveness.
Strengthen Traceability for Embedded Passive Integration
As buried capacitor integration gains traction in flagship designs, procurement and QA teams must verify material lot traceability down to resin batch and capacitor thin-film deposition parameters — a requirement now reflected in updated Samsung Q2 2026 HDI sourcing guidelines.
Review Logistics Partnerships for Time-Bound Delivery Windows
With lead times compressed to ≤8 weeks, end-to-end transit time variability — including port dwell, customs clearance, and inland transport — can no longer be treated as secondary. Firms should audit current logistics SLAs and consider dual-sourcing regional fulfillment nodes (e.g., Shenzhen + Ho Chi Minh City bonded hubs).
Editorial Perspective / Industry Observation
Analysis shows this 1% shipment growth is not indicative of broad-based recovery in mid-tier smartphone demand — rather, it reflects selective strength in premium segments where design complexity (e.g., foldables, AI-accelerated imaging stacks) drives substrate-level innovation. Observably, the fact that Tier-1 OEMs are awarding additional HDI orders *before* full-scale Q2 product launches suggests confidence in both supply readiness and technical alignment. From an industry perspective, this points less to cyclical rebound and more to a step-change in China’s HDI substrate ecosystem maturity — particularly in metrology-controlled sequential build-up and impedance-matched via formation.
Conclusion
This development does not signal a wholesale revival of smartphone hardware investment, but it does confirm a durable inflection point: HDI substrate capability is transitioning from a ‘cost-aggregation’ component to a ‘design-enabling’ subsystem. For stakeholders across the value chain, the implication is clear — technical agility, not just scale, now defines competitive advantage.
Source Attribution
Data sourced from Omdia’s Smartphone Component Forecast Report, Q2 2026 Edition (released May 18, 2026). Customer order confirmations were provided by three publicly listed Active Components manufacturers under non-disclosure agreement terms. Ongoing monitoring is recommended for: (1) Q2 2026 regional shipment breakdowns (particularly China domestic vs. export), (2) Samsung’s updated HDI specification revision (v3.2), expected June 2026, and (3) U.S. Bureau of Industry and Security updates on substrate-related export licensing criteria.
The Archive Newsletter
Critical industrial intelligence delivered every Tuesday. Peer-reviewed summaries of the week's most impactful logistics and market shifts.