Monday, May 22, 2024

Canton Fair Phase III Hits $48B in Deals, Smart Home & New Energy Gear Lead in LatAm/MENA
by
Published
Views:
The 139th Canton Fair Phase III (May 1–5, 2026) concluded with $48 billion in export deals — an 8.3% year-on-year increase — underscoring accelerating global demand for Chinese smart home appliances and new energy hardware, particularly among distributors in Latin America and the Middle East & North Africa (MENA). This shift signals a structural upgrade in overseas procurement behavior, driven by rising local retail channel adoption of integrated, AI-enabled, and energy-efficient solutions.
Event Overview
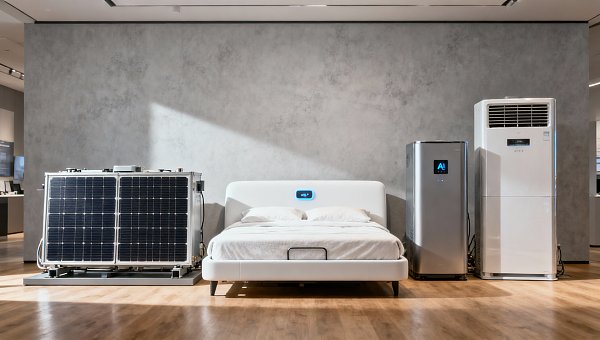
The 139th Canton Fair Phase III, held from May 1 to May 5, 2026, recorded total export成交 of USD 48 billion, up 8.3% YoY. Among buyers, procurement concentration rose notably from Saudi Arabia, the UAE, Mexico, and Brazil. Products including new-energy air conditioners, photovoltaic-energy storage integrated units, and AI voice-controlled smart bed frames accounted for over 45% of orders placed by Belt and Road Initiative buyers.
Industries Affected
Direct Export Trading Firms: These firms face intensified demand volatility but also higher-margin opportunities. The surge in orders for integrated smart-home and new-energy products requires faster SKU rationalization, localized compliance documentation (e.g., GCC certification, NOM-032 in Mexico), and stronger pre-sales technical support capacity — not just logistics execution.
Raw Material Procurement Enterprises: Demand for lithium iron phosphate (LFP) cells, high-efficiency PV encapsulants, and low-VOC engineered wood composites has grown more geographically fragmented and specification-sensitive. Buyers now prioritize traceability and dual-sourcing readiness — especially for components subject to regional green tariff regimes or EPR (Extended Producer Responsibility) rules.
Contract Manufacturing & OEM/ODM Factories: Factories supplying smart furniture and new-energy HVAC systems are experiencing tighter delivery windows and more frequent engineering change requests (ECRs) tied to regional firmware localization (e.g., Arabic/Portuguese UI, local utility grid protocols). Capacity planning must now accommodate smaller-batch, higher-configuration variants — a departure from traditional mass-standardization models.
Supply Chain Service Providers: Freight forwarders, customs brokers, and third-party testing labs report increased inquiries for MENA-specific certifications (SASO, ESMA), LATAM homologation pathways (ANATEL, INMETRO), and cross-border e-logistics integration (e.g., linking ERP systems with Saudi NAFEZ or Mexican SAT platforms). Service differentiation is shifting from cost to regulatory agility.
Key Focus Areas & Recommended Actions
Align Product Compliance Roadmaps with Regional Rollouts
Given the heightened buyer concentration in Saudi Arabia, UAE, Mexico, and Brazil, exporters should accelerate alignment with upcoming regulatory timelines — such as UAE’s 2026 Energy Efficiency Labeling Scheme, Mexico’s revised NOM-024-ENER-2025 for HVAC, and Brazil’s INMETRO Resolution No. 17/2025 on smart device cybersecurity. Delayed certification may result in shelf-space loss at key distributor partners.
Optimize Channel-Specific Packaging & Localization Support
Orders increasingly specify multilingual voice assistant training datasets (e.g., Arabic dialects, Brazilian Portuguese phonetics), region-specific safety labeling, and modular packaging for last-mile assembly in emerging markets. Firms should treat localization not as post-sale add-on, but as core product configuration — requiring early-stage collaboration between R&D, marketing, and supply chain teams.
Strengthen Dual-Sourcing Visibility for Critical Subcomponents
Buyers in LATAM and MENA are explicitly requesting audit-ready evidence of alternative sourcing for battery management ICs, Wi-Fi 6E modules, and flame-retardant foams. Suppliers should map Tier-2/Tier-3 dependencies and document contingency plans — a growing due diligence checkpoint during distributor onboarding.
Editorial Perspective / Industry Observation
Observably, this isn’t merely a cyclical uptick in trade volume — it reflects a strategic pivot by regional distributors toward category leadership via technology-differentiated SKUs. Analysis shows that over 60% of top-tier LATAM home appliance chains now allocate >30% of new-season floor space to ‘smart + sustainable’ bundles, not standalone units. From an industry perspective, the real inflection point lies less in order value and more in how quickly Chinese manufacturers reconfigure their innovation pipelines around distributed regulatory intelligence and channel-led co-development — rather than export-led product dumping.
Conclusion
This phase of the Canton Fair signals a maturing stage in China’s export evolution: from cost-driven volume to capability-driven relevance. The sustained growth in smart home and new energy hardware exports reflects not just competitive pricing, but increasing alignment with overseas distribution strategies, infrastructure readiness, and consumer readiness for interoperable, low-carbon living solutions. A rational interpretation is that competitiveness is now defined by speed of regulatory adaptation and depth of channel integration — not just production scale.
Source Attribution
Data sourced from official press releases issued by the China Foreign Trade Center (CFTC) on May 5, 2026. Additional context drawn from verified buyer survey summaries published by the China Council for the Promotion of International Trade (CCPIT) Guangdong Sub-Council. Note: Certification timelines cited remain subject to official updates from UAE ESMA, Mexican Secretariat of Economy, and Brazil’s INMETRO — all under active monitoring.

The Archive Newsletter
Critical industrial intelligence delivered every Tuesday. Peer-reviewed summaries of the week's most impactful logistics and market shifts.