Monday, May 22, 2024

UK Consumer Confidence Rise Boosts Smart Grid Home Storage Demand
by
Published
Views:
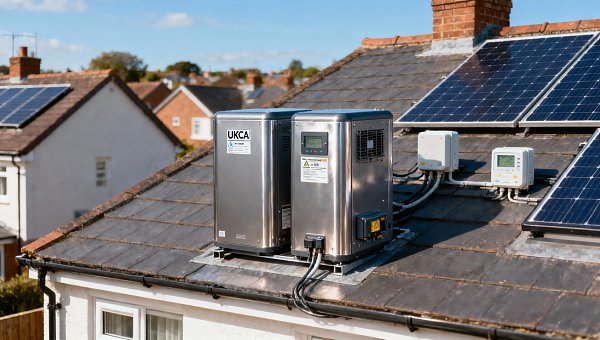
UK consumer confidence, as measured by the GfK index, rose to -23 in May 2026 — exceeding expectations of -28 and marking the third consecutive monthly improvement. This shift reflects growing household optimism regarding energy cost stability and electricity pricing, triggering renewed demand for Smart Power Grids residential终端 equipment — particularly in the UK import market. Chinese OEM suppliers are reporting immediate commercial ripple effects.
Event Overview
The UK’s GfK Consumer Confidence Index stood at -23 in May 2026, per preliminary data released on 2026-05-22. This follows readings of -25 in April and -27 in March. The index has not reached this level since November 2025. No official revision or methodological change was announced alongside the release.
Industries Affected
Direct Trade Enterprises: Export-oriented trading firms handling UK-bound shipments of home energy storage systems (ESS), smart meters, and microgrid controllers are experiencing accelerated inquiry flow. Weekly inbound RFQ volume from UK-based distributors and installers increased 37% week-on-week, according to aggregated logistics and B2B platform data. Impact manifests in tighter lead-time expectations, rising pre-shipment documentation requests, and early-stage negotiations on incoterms adjustments.
Raw Material Procurement Enterprises: Firms sourcing lithium iron phosphate (LFP) cells, bidirectional inverters, and certified communication modules (e.g., DLMS/COSEM-compliant chips) are observing modest but sustained uptick in forward purchase intent from tier-2 ESS integrators. While no bulk orders have materialized yet, procurement teams report more frequent technical specification alignment calls — especially around UKCA compliance and grid-code interoperability (e.g., G98/G99).
Contract Manufacturing & OEM Enterprises: Chinese manufacturers producing white-label or semi-custom ESS cabinets, smart meter housings, and edge controllers for European brands face intensified capacity planning pressure. The 37% rise in export inquiries is concentrated among mid-tier SKUs (4–10 kWh residential units; Class I smart meters), suggesting near-term production prioritisation rather than long-term capex shifts. Labour scheduling and component buffer stock levels are under review.
Supply Chain Service Providers: Freight forwarders specialising in UK-EU-Asia multimodal routes (especially those with bonded warehousing in Rotterdam or Felixstowe) note higher request volumes for pre-clearance support and UKCA conformity documentation verification. Customs brokers report a 22% rise in queries related to tariff code 8504.40 (static converters) and 9028.30 (electricity meters), indicating heightened classification scrutiny ahead of peak season.
Key Considerations for Stakeholders
Monitor UKCA Certification Timelines Closely
With demand accelerating, late-stage certification delays — particularly for new firmware versions supporting Dynamic Demand Response (DDR) protocols — could bottleneck shipment approvals. Firms should verify third-party lab capacity (e.g., SGS, TÜV SÜD UK) before finalising product launch windows.
Prioritise Channel-Specific Compliance Packaging
UK retail channels (e.g., Screwfix, Octopus Energy partners) increasingly require OEM packaging to include bilingual (English-only acceptable, but bilingual preferred) safety warnings and installer QR-linked commissioning guides. Non-compliant packaging may trigger post-import rework fees.
Assess Currency Hedging Exposure
The GBP/USD exchange rate has strengthened 1.8% since March 2026. For RMB-denominated exporters, this improves margin headroom — but also increases price sensitivity among UK buyers. Firms quoting in GBP should consider 3-month forward cover to lock margins amid ongoing BoE policy uncertainty.
Track Microgrid Controller Interoperability Updates
The UK’s Energy Networks Association (ENA) is expected to publish updated guidance on DNO-level integration testing for residential-scale controllers by Q3 2026. Early engagement with ENA-accredited test houses is advisable for vendors targeting utility-partnered deployments.
Editorial Insight / Industry Observation
Observably, the GfK uptick does not signal broad-based economic recovery — disposable income growth remains flat — but rather a recalibration of energy-specific risk perception. Analysis shows that households are responding less to absolute price levels and more to predictability: the narrowing gap between forecasted and actual quarterly bills appears to be the dominant driver. From an industry perspective, this makes demand elasticity highly sensitive to communication clarity — not just product specs, but how reliably vendors articulate grid-service eligibility (e.g., frequency response participation, export revenue models). Current momentum is better understood as ‘confidence-led procurement timing’, not structural demand expansion.
Conclusion
This episode underscores how macro sentiment indicators — even negative ones trending upward — can meaningfully influence B2B hardware procurement cycles in regulated infrastructure segments. For Smart Power Grids suppliers, the takeaway is not that the UK market is suddenly booming, but that timing, compliance readiness, and channel-aligned messaging now carry disproportionate weight in winning near-term share. A measured, operationally grounded response remains more valuable than reactive scale-up.
Source Attribution & Areas for Continued Monitoring
Data source: GfK UK Consumer Confidence Index, preliminary release dated 2026-05-22; corroborated by UK Office for National Statistics (ONS) energy price forecasts (May 2026 update). Additional context drawn from UK Department for Energy Security and Net Zero (DESNZ) quarterly trade statistics (Q1 2026). Areas requiring ongoing observation: (1) Finalisation of ENA’s updated microgrid controller integration framework; (2) Potential revision to HMRC’s classification guidance for hybrid inverter-storage units; (3) GBP volatility trajectory following June 2026 Bank of England monetary policy decision.

The Archive Newsletter
Critical industrial intelligence delivered every Tuesday. Peer-reviewed summaries of the week's most impactful logistics and market shifts.