Monday, May 22, 2024
Saudi East-West Pipeline Pump Station Damaged, Wastewater & Filtration Logistics Costs Rise 7–12%
by
Published
Views:
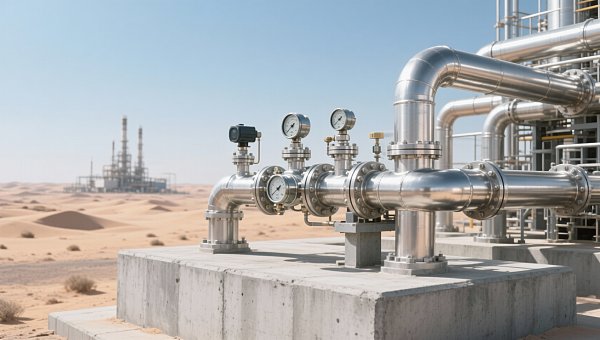
Recent damage to a pump station on Saudi Arabia’s East-West Crude Oil Pipeline has disrupted regional energy infrastructure and triggered measurable cost increases for global shipments of Wastewater & Filtration equipment—particularly membrane bioreactor (MBR) modules, high-pressure valves and pumps, and smart monitoring terminals. Though the exact date of the incident is not publicly confirmed, its operational and logistical ripple effects are now evident across industrial gas, LPG, and specialty chemical supply chains in the Middle East—and increasingly visible in maritime freight pricing and customs processing times for filtration-related exports from China to Europe and Africa.
Event Overview
Saudi energy infrastructure sustained damage affecting a key pump station along the East-West Crude Oil Pipeline. As a result, the pipeline’s daily throughput capacity declined by 700,000 barrels. This disruption has indirectly impacted the transportation network for industrial gases, liquefied petroleum gas (LPG), and specialty chemicals across the Middle East. Concurrently, maritime logistics costs—including surcharges and insurance premiums—for Wastewater & Filtration equipment transiting via the Red Sea–Suez Canal route have risen by 7–12%. Some European and African importers report customs clearance delays of 2–3 additional working days. Chinese exporters are advised to proactively communicate potential delivery delays and cost-sharing arrangements to overseas customers.
Which Sub-Sectors Are Affected
Direct Exporters (e.g., Chinese Wastewater & Filtration Equipment Manufacturers)
These firms face higher outbound logistics costs and longer lead times due to revised shipping surcharges and extended customs processing. The impact is most acute for time-sensitive orders involving MBR membrane assemblies or integrated smart monitoring systems shipped through Suez-linked routes.
Raw Material & Component Importers (e.g., Gulf-based Filtration System Integrators)
Importers relying on critical spares—such as high-pressure diaphragm valves or sensor modules sourced from Asia—are encountering tighter availability windows and elevated landed costs. Delays compound where local assembly depends on just-in-time component arrivals.
Industrial End-Users (e.g., Petrochemical Plants, Municipal Wastewater Operators in MENA)
Operators planning upgrades or maintenance cycles may face revised procurement timelines and budget adjustments, especially if their projects depend on imported filtration hardware subject to Suez transit constraints.
Logistics & Supply Chain Service Providers (e.g., Freight Forwarders Specializing in Industrial Equipment)
Providers managing multimodal shipments of filtration systems must now factor in dynamic insurance recalculations, alternative routing advisories (e.g., Cape of Good Hope detours), and updated documentation requirements for hazardous or regulated components.
What Relevant Enterprises or Practitioners Should Monitor and Do Now
Track official updates on Red Sea–Suez passage advisories and insurance underwriting guidelines
Maritime insurers and classification societies (e.g., Lloyd’s, DNV) have issued updated risk assessments for vessels transiting the Red Sea. Exporters and forwarders should monitor these for real-time implications on cargo coverage terms and premium adjustments.
Review shipment schedules for MBR modules, high-pressure pump valves, and smart monitoring terminals bound for Europe or Africa
These product categories are explicitly cited in the cost increase notice. Prioritize re-forecasting delivery windows and validating whether contractual Incoterms allow for cost pass-through or timeline renegotiation.
Distinguish between policy-level risk signals and actual operational impacts
The 7–12% logistics cost rise reflects current market pricing—not a formal tariff or regulatory mandate. Its duration and scope remain contingent on evolving security conditions and insurer response; therefore, treat it as a near-term volatility indicator rather than a structural shift.
Pre-notify international buyers of potential delays and jointly develop contingency plans
Chinese exporters should initiate proactive communication with EU and African clients—especially those with fixed commissioning dates—providing transparent timelines, revised cost breakdowns, and options such as phased deliveries or alternative port-of-discharge selections.
Editorial Perspective / Industry Observation
Observably, this incident functions less as an isolated infrastructure failure and more as a stress test for global industrial filtration supply chains reliant on narrow maritime corridors. Analysis shows that even localized physical disruptions in energy-critical zones can propagate quickly into specialized equipment logistics—particularly where technical components require certified handling, tight tolerances, and time-bound installation. From an industry perspective, it highlights how wastewater and filtration hardware—often treated as secondary procurement items—now sits at a strategic intersection of energy security, maritime risk, and industrial resilience. Current developments are better understood as an early-stage signal: while immediate cost and timing impacts are confirmed, broader rerouting trends or long-term modal shifts (e.g., increased air freight use for critical spares) remain unconfirmed and warrant ongoing observation.
In summary, the pump station incident is not merely an energy-sector event—it reveals latent dependencies in the global filtration equipment value chain. Its significance lies in exposing how geopolitical and infrastructural vulnerabilities in one domain translate directly into cost, timing, and coordination challenges for manufacturers, integrators, and end-users across water, chemical, and energy-adjacent industries. At present, it is more accurate to interpret this development as a short-to-medium term operational pressure point—not a permanent restructuring—but one requiring disciplined monitoring and agile response protocols.
Source(s): Public statements from Saudi energy authorities (unspecified date); maritime insurance bulletin data (Q2 2024); logistics cost indices from major freight forwarding associations (Red Sea–Suez corridor segment). Note: The exact date of the incident remains unconfirmed and is under continued observation.
The Archive Newsletter
Critical industrial intelligence delivered every Tuesday. Peer-reviewed summaries of the week's most impactful logistics and market shifts.