Monday, May 22, 2024

Japan's Bank Loan Rate Hits 5.4%, Cuts Manufacturing Import Demand
by
Published
Views:
Japan’s April bank loan annual growth rate rose to 5.4%—its highest in three years—according to data released on May 13, 2026. This sharp uptick signals tightening domestic financing conditions for manufacturers, with downstream implications for cross-border procurement patterns, particularly for high-value equipment imported from China.
Event Overview
On May 13, 2026, Japan’s Ministry of Finance and Bank of Japan jointly published seasonally adjusted data showing the annual growth rate of outstanding bank loans reached 5.4% in April 2026, up from 4.8% in March. The figure marks the strongest year-on-year expansion since early 2023.
Industries Affected
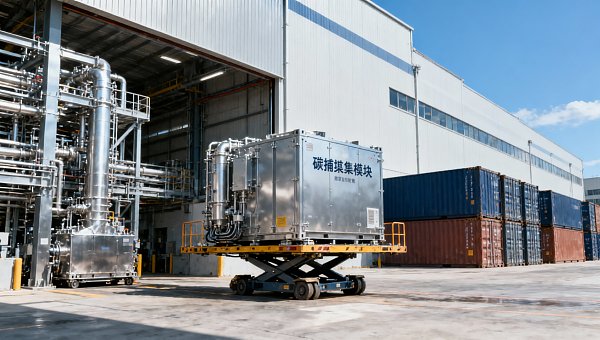
Direct Export Enterprises: Chinese firms exporting powertrain systems, carbon capture modules, and smart irrigation systems to Japanese end-users face delayed order execution. As Japanese manufacturers reassess capital expenditure plans amid rising borrowing costs, budget approvals for imported high-end equipment are slowing—not due to demand erosion, but due to financing friction and internal ROI recalibration.
Raw Material Procurement Enterprises: Suppliers of specialty alloys, rare-earth components, or sensor-grade semiconductors used in those exported systems may see softer near-term order visibility. While not directly exposed to Japanese lending rates, their forward planning is now contingent on longer lead times and more conservative forecasts from downstream OEMs and system integrators in Japan.
Contract Manufacturing & Assembly Firms: Chinese EMS (electronics manufacturing services) and mechanical assembly providers supporting Japanese clients’ localized production of integrated systems may encounter revised delivery schedules or paused pilot runs. Higher cost of capital in Japan reduces urgency for rapid scale-up of new product lines reliant on imported core subsystems.
Supply Chain Service Providers: Logistics firms, customs brokers, and trade finance intermediaries serving Sino-Japanese equipment trade must anticipate increased documentation scrutiny, longer credit verification cycles, and higher frequency of payment term renegotiations—especially where buyers seek extended D/A or deferred LC structures.
Key Focus Areas and Recommended Actions
Adapt Financing Offerings for Japanese Buyers
Chinese exporters should prioritize co-developing flexible payment solutions—including structured installment plans, vendor leasing arrangements, and third-party financing partnerships with Japanese leasing companies—to offset elevated local borrowing costs. This is not merely a sales tactic but a necessary alignment with Japan’s current capital allocation reality.
Reassess Quotation Timelines and Contract Clauses
Given observed delays in Japanese CAPEX approval cycles, quoting validity periods should be shortened (e.g., 30–45 days), and contracts should include explicit force-majeure-style clauses covering “financing conditionality” — allowing for renegotiation if buyer credit access materially deteriorates post-signing.
Strengthen Local Technical Support Infrastructure
To reinforce value beyond price, exporters should expand on-the-ground technical service capacity in Japan—including certified field engineers, remote diagnostics support, and modular commissioning packages—reducing buyers’ perceived risk of integrating complex imported systems amid tighter internal budgets.
Editorial Perspective / Industry Observation
This development is better understood as a liquidity-driven pause—not a structural reversal—in Japan’s industrial upgrading trajectory. Analysis shows that capex intentions remain intact across energy transition and food security sectors; however, implementation timelines are stretching. Observably, Japanese firms are shifting from ‘buy-now’ to ‘buy-right’, prioritizing total cost of ownership over upfront price. From an industry standpoint, this favors Chinese suppliers with strong lifecycle service capabilities and transparent TCO modeling—not just competitive unit pricing.
Conclusion
The 5.4% loan growth rate reflects a temporary but meaningful inflection in Japan’s domestic financial environment—not a weakening of long-term strategic import needs. For Chinese exporters, the implication is not reduced opportunity, but a requirement to deepen financial, technical, and contractual sophistication in bilateral engagements. A measured, responsive posture will separate resilient players from those reliant on historical transaction patterns.
Source Attribution
Data sourced from the Bank of Japan’s Monthly Report on Currency and Finance (May 2026 edition) and the Ministry of Finance’s Bank Lending Statistics, both released on May 13, 2026. Continued monitoring is advised for June’s corporate sentiment survey (Tankan) and upcoming BOJ policy board minutes—both expected to clarify whether this trend reflects transitory inflation hedging or a sustained shift in monetary stance.

The Archive Newsletter
Critical industrial intelligence delivered every Tuesday. Peer-reviewed summaries of the week's most impactful logistics and market shifts.