Monday, May 22, 2024
Maersk Red Sea Return May Pressure FEU-Europe Rates
by
Published
Views:
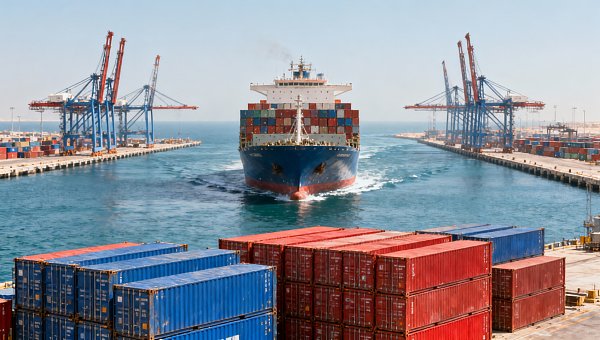
On May 14, 2026, Maersk’s CEO confirmed that the company is evaluating a phased return to the Red Sea and Suez routing in Q3 and Q4, after the frequency of Houthi attacks declined for two consecutive months. For the shipping, export, procurement, and supply chain service segments, this is worth close attention not simply as a route update, but as a possible execution signal that transport rules, capacity allocation, freight quotations, and delivery planning could begin to shift if carriers move back in stages.
A confirmed change in routing assessment and market signals
The confirmed facts are limited but commercially significant. Maersk stated on May 14, 2026 that it is assessing a phased restoration of Red Sea and Suez services during Q3 and Q4. The stated reason is that the frequency of Houthi attacks has fallen for two straight months. The event summary also states that if the Gemini and MSC alliances switch on a similar timetable, global effective deep-sea capacity could be released by 6% to 8%, which would directly challenge the current high freight-rate structure. In addition, the SCFI composite index had already softened by June 15, while the U.S. West Coast route fell 2.8% in a single week, and peak-season booking rhythms had been disrupted.
Where the operational pressure may appear first
Export shippers may need to revisit freight and delivery assumptions
From an industry perspective, exporters are among the first groups likely to feel the impact because route normalization, even if only partial, can alter freight expectations, booking timing, and customer delivery commitments. What deserves closer attention is whether existing quotations, shipment schedules, and contract delivery windows were built around the higher-cost routing environment. If so, companies may need to review shipping clauses, booking documents, and delivery commitments with greater frequency.
Procurement teams may face new timing and landed-cost adjustments
For raw material buyers and procurement-driven manufacturers, the main issue is not only whether freight rates fall, but how quickly transport assumptions used in purchasing plans become outdated. Analysis shows that a phased return discussion can affect landed-cost calculations, reorder timing, and supplier communication. Businesses should pay attention to any changes in shipment lead times, freight validity periods, and procurement documents that rely on prior routing assumptions.
Supply chain service providers may need tighter execution controls
Freight forwarders, logistics coordinators, and related supply chain service providers could be affected through booking allocation, transit planning, and document consistency. If market participants start adjusting routes in anticipation of restored Red Sea and Suez usage, service providers may need to monitor carrier notices, booking terms, transport instructions, and customer-facing delivery commitments more closely. The practical focus is less about a confirmed market reset and more about managing execution differences during a possible transition phase.
What companies should monitor before treating this as a settled shift
Watch for formal wording and actual execution steps
Analysis shows that the current development should not yet be treated as a completed routing rule change. The key issue is whether future carrier wording moves from assessment to confirmed implementation. Companies should therefore track follow-up statements, operating notices, and any revised service arrangements before changing long-term shipping or procurement strategies.
Review contracts and shipping documents tied to prior assumptions
Observably, any business that priced goods, promised delivery, or arranged procurement under the previous high-rate environment may need to recheck contract language, booking records, quotation validity, and shipment planning documents. This is especially relevant where transport cost assumptions affect customer offers, supplier negotiations, or delivery responsibility allocation.
Keep procurement and inventory plans flexible
From an industry perspective, disrupted peak-season booking rhythms suggest that timing risk remains as important as rate direction. Companies may therefore need to keep procurement schedules, replenishment cycles, and shipment batching flexible rather than assuming that lower freight rates automatically mean smoother execution.
Do not overread early market weakness as a final trend
Analysis shows that the softer SCFI reading and the weekly decline on the U.S. West Coast route are meaningful signals, but they do not by themselves confirm a fully established new pricing regime. Businesses should focus on how market feedback, carrier execution, and booking behavior develop over time.
Why this looks more like an execution signal than a finished rule reset
It is more appropriate to understand this as an early operational and market signal rather than a fully settled industry rule change. The confirmed element is the evaluation of a phased return and the market sensitivity around possible capacity release. What deserves closer attention is whether this assessment turns into coordinated execution and whether the resulting changes affect route selection, freight validity, delivery promises, and tender or procurement documentation. For now, the development sits between security-related operational adjustment and broader commercial repricing, which means industry participants still need to separate confirmed facts from expected outcomes.
How the market should read the development for now
In practical terms, this event matters because it may begin to reshape freight assumptions that many exporters, buyers, and logistics providers have been using under a disrupted routing environment. At the same time, the information currently available supports caution rather than certainty. The most balanced reading is that this is a credible transition signal with potential implications for transport execution, procurement planning, and delivery management, but it still requires continued observation before being treated as a settled market rule.
Basis of this article and points that still require verification
This article is generated from the user-provided news title, event date, and event summary. For developments of this kind, commonly relevant source types may include official company announcements, regulatory releases, customs or trade authority information, industry association updates, standard-setting documents, and reporting by authoritative media. No specific official source link was provided in the input, so the exact official reference path still needs ongoing verification. Observably, the next points to monitor include later implementation details, operational wording, tender-document changes, market feedback, and how companies adjust execution in response.
The Archive Newsletter
Critical industrial intelligence delivered every Tuesday. Peer-reviewed summaries of the week's most impactful logistics and market shifts.