Monday, May 22, 2024

realme Halts Domestic Foldable R&D, Shifts Capacity to SEA & MENA ODM
by
Published
Views:
On May 5, 2026, realme announced the suspension of its domestic small-fold smartphone development and redirected production capacity from its Shenzhen/Dongguan facilities toward ODM orders for Southeast Asia and the Middle East. This shift directly impacts suppliers of high-integration powertrain control modules, ADAS camera bracket injection-molded components, and custom plastic injection molds — making these segments critical for trade, manufacturing, and supply chain stakeholders.
Event Overview
According to a report by IT Home dated May 5, 2026, realme has paused R&D on small-form-factor foldable smartphones for the Chinese domestic market. Its primary production lines in Shenzhen and Dongguan are now prioritizing ODM (Original Design Manufacturing) orders destined for Southeast Asian and Middle Eastern markets. These orders include high-integration Powertrain Systems control modules, precision injection-molded ADAS camera mounting brackets, and customized Plastic Injection Molds. Multiple Tier-2 Chinese suppliers have received rolling production planning confirmations covering a 6–9 month horizon.
Industries Affected
Direct Trading Enterprises
Trading firms engaged in cross-border export of electronic components or precision mechanical parts may face revised order volumes and regional demand concentration. The shift signals stronger near-term demand for SEA/MENA-bound consignments — particularly for automotive-grade plastic assemblies and embedded control modules — while domestic-tiered distribution channels for foldable-phone peripherals may soften.
Raw Material Procurement Firms
Suppliers of engineering-grade thermoplastics (e.g., PBT, PPS, LCP), metal-plastic hybrid substrates, and precision mold steels may observe shifting procurement patterns. Orders tied to realme’s new ODM scope emphasize thermal stability, dimensional accuracy, and multi-cavity mold compatibility — criteria that influence raw material grade selection and lead-time planning.
Contract Manufacturing & Precision Molding Firms
Firms specializing in high-tolerance injection molding, insert molding, or mechatronic module assembly are directly exposed to this capacity reallocation. Realtime adjustments in tooling utilization, cycle time optimization, and validation protocols for automotive-spectrum ADAS components become operationally urgent — especially given the 6–9 month rolling forecast window.
Supply Chain Service Providers
Logistics integrators, customs brokerage services, and quality assurance labs supporting electronics exports must anticipate increased documentation complexity for dual-market compliance (e.g., GCC conformity, ASEAN MRA alignment) and tighter delivery windows for serialized mold tooling shipments.
What Enterprises and Practitioners Should Monitor and Act On
Track official realme communications on regional ODM strategy
While the May 5 announcement confirms capacity redirection, realme has not published formal product roadmaps or long-term volume commitments for SEA/MENA ODM. Stakeholders should monitor upcoming investor briefings or partner ecosystem updates for clarity on program duration, tiered supplier engagement models, and potential expansion into adjacent verticals (e.g., smart mobility infrastructure).
Validate demand continuity for specific component categories
The cited ODM scope focuses narrowly on Powertrain Systems control modules, ADAS camera brackets, and custom plastic molds — not full-device assembly or consumer UI hardware. Companies should verify whether their current product portfolio aligns precisely with these three categories before adjusting capacity or quoting terms.
Distinguish between confirmed production allocation and strategic intent
The reported capacity shift reflects an operational decision based on near-term order visibility (6–9 months), not necessarily a permanent exit from domestic foldable development. Suppliers should avoid interpreting this as a structural market withdrawal; instead, treat it as a tactical load-balancing move requiring flexible rescheduling—not wholesale retooling.
Prepare for accelerated qualification cycles and regional compliance checks
ODM engagements for automotive-adjacent systems in SEA/MENA often require faster PPAP timelines and localized test reports (e.g., SIRIM, ESMA, SASO). Firms should pre-align internal QA workflows with applicable regional standards and confirm third-party lab readiness ahead of formal PO issuance.
Editorial Observation / Industry Perspective
Observably, this move reflects a broader recalibration among Chinese OEMs toward higher-margin, lower-volume, regionally tailored ODM opportunities — particularly where regulatory tailwinds (e.g., ASEAN EV incentives, GCC localization mandates) support rapid deployment of modular subsystems. Analysis shows realme’s pivot is less about abandoning the domestic foldable segment and more about optimizing asset utilization amid softening premium smartphone demand in China. It functions primarily as an operational signal — one indicating short-to-midterm capacity reprioritization rather than a strategic inflection point. The industry should therefore track follow-up indicators: changes in realme’s Tier-1 supplier disclosures, shifts in Shenzhen/Dongguan industrial park utility load data, and updates to export HS code filings for molded plastic parts under Chapter 39.
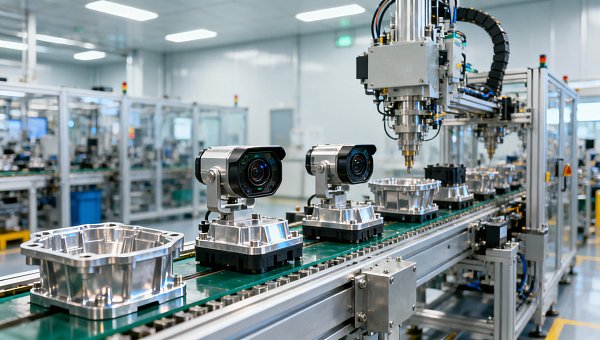
In summary, realme’s production reallocation underscores how regional ODM demand — especially in automotive-adjacent electronics — is reshaping capacity decisions among Chinese contract manufacturers. This is not a market exit but a focused recalibration: one demanding precise component-level alignment, disciplined regional compliance readiness, and continuous monitoring of downstream order visibility — not broad strategic overhauls.
Source: IT Home (report dated May 5, 2026). Note: realme’s official statements on long-term domestic foldable plans and SEA/MENA ODM roadmap remain pending — continued observation recommended.

The Archive Newsletter
Critical industrial intelligence delivered every Tuesday. Peer-reviewed summaries of the week's most impactful logistics and market shifts.