Monday, May 22, 2024
Indonesian Rupiah Hits Record Low, Raising Import Costs
by
Published
Views:
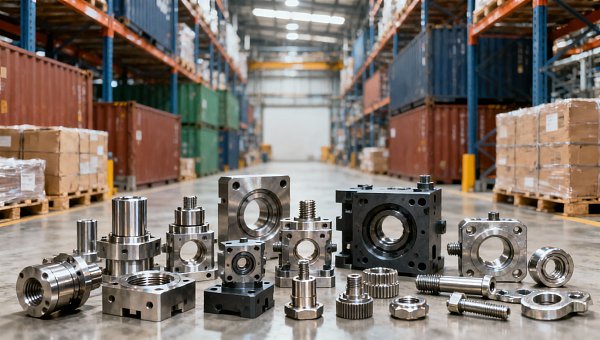
On June 5, 2026, the Indonesian rupiah fell to a record low against the U.S. dollar, increasing local-currency purchasing pressure for Indonesian importers buying industrial goods from China, including CNC machined parts, injection molds, and hardware components. For companies involved in cross-border sourcing, distribution, delivery, and after-sales support, this development is worth close attention because it is already influencing procurement decisions and channel strategies in the Indonesian market.
What has been confirmed so far
The confirmed information is limited but clear. On June 5, 2026, the rupiah broke below its previous historical low against the U.S. dollar. This has increased the local-currency cost burden on Indonesian importers purchasing Chinese industrial products.
The product categories specifically mentioned include CNC machined parts, injection molds, and hardware components. It has also been confirmed that some Indonesian distributors have already started adopting localized assembly and secondary inventory strategies.
The same development indicates that Chinese exporters need to accelerate three practical capabilities for the Indonesian market: Indonesian-language technical documentation, local after-sales response commitments, and DAP/DDP delivery options.
Where the pressure is likely to appear across the chain
Import purchasing is facing immediate cost sensitivity
From an industry perspective, the most direct impact falls on Indonesian importers and purchasing teams. Because transactions for imported industrial goods are commonly linked to foreign-currency pricing, a weaker rupiah can make the same order more expensive in local terms. The pressure is likely to show up first in quotation acceptance, reorder timing, and purchasing volume decisions.
What deserves closer attention is whether buyers begin to shift from straightforward import replenishment toward more cautious ordering, staged procurement, or a stronger preference for suppliers that can reduce total landed-cost uncertainty.
Distributors are adjusting channel and inventory logic
The confirmed move by some Indonesian distributors toward localized assembly and secondary inventory suggests that channel players are not only reacting to price pressure but also trying to improve flexibility. Analysis shows that this can affect how imported components are stocked, how finished or semi-finished goods are positioned locally, and how delivery responsiveness is managed for downstream customers.
For distributors, the issue is not only cost inflation. It is also about preserving service continuity while limiting exposure to exchange-rate swings on every replenishment cycle.
Chinese exporters may face new demands beyond price
For Chinese manufacturers and exporters of CNC parts, molds, and hardware components, the implication is broader than quotation competitiveness alone. Buyers under currency pressure may place greater weight on documentation clarity, communication efficiency, delivery term transparency, and after-sales reliability.
Observably, suppliers that still rely on English-only technical materials or unclear delivery responsibility may face higher friction in negotiation, approval, and post-delivery support, even if product specifications remain unchanged.
Supply chain service providers may see changing delivery expectations
Logistics and trade service participants may also feel the effect through a change in client expectations. The specific mention of DAP/DDP options suggests that customers may increasingly value delivery structures that provide more predictable responsibility allocation and cost visibility. The practical impact is likely to be strongest in quotation structure, customs-handling coordination, and last-mile delivery commitment.
What companies should prioritize now
Improve Indonesian-language technical readiness
The clearest operational signal in this update is the need for Indonesian-language technical documentation. Companies serving Indonesia should review whether product drawings, installation instructions, operating notes, maintenance guidance, and key specification materials can be understood and used locally without unnecessary translation delays.
This is not a branding issue; it is a transaction and execution issue. In a more cost-sensitive market, any ambiguity in technical communication can slow approvals and increase hesitation in procurement.
Make after-sales response commitments more concrete
The event summary specifically points to local after-sales response commitments. Analysis shows that when import costs rise, buyers may become more cautious about post-purchase risk. In that context, responsiveness after delivery becomes part of the buying decision rather than a secondary service feature.
Companies should pay attention to whether their current support process can clearly answer who responds, in what language, and within what timeframe. Even without changing the product itself, clearer service commitments may become more important in maintaining customer confidence.
Review delivery terms and landed-cost communication
The mention of DAP/DDP options highlights a practical area that exporters and service partners should reassess. Buyers facing currency pressure may prefer delivery models that simplify import-side handling and improve cost predictability.
What deserves closer attention is not only whether DAP or DDP can be offered, but whether the commercial terms are explained clearly enough for Indonesian customers to compare options in local decision-making contexts.
Watch how localization and secondary inventory evolve
The confirmed adoption of localized assembly and secondary inventory by some distributors should be monitored closely. Observably, this is relevant not only for channel companies in Indonesia but also for upstream exporters deciding product mix, packaging format, shipment batch structure, and replenishment planning.
At this stage, it would be premature to treat this as a universal market shift. Still, it is a practical signal that some buyers are looking for ways to reduce direct exposure to currency-driven import pressure.
Why this matters beyond a single exchange-rate move
Analysis shows that this development should not be read only as a foreign-exchange headline. In the industrial goods trade, exchange-rate pressure can quickly turn into changes in sourcing behavior, inventory design, and service expectations. The fact that localized assembly, secondary inventory, Indonesian-language documentation, and DAP/DDP delivery are all appearing in the same context makes this especially relevant for companies with active Indonesia-facing business.
It is more appropriate to understand this as a market signal with immediate operational implications, rather than as a fully formed long-term trend. The confirmed facts show early adjustment behavior, but they do not yet establish a final market outcome.
How this update is best understood at this stage
At present, this update points to rising transaction pressure in Indonesia's import chain for selected industrial goods from China. The most visible issue is higher local-currency procurement cost, but the more important industry takeaway is the shift in practical buyer requirements: clearer local-language materials, more dependable after-sales structure, and delivery terms that reduce uncertainty.
A neutral reading is that this is a short-term shock with the potential to influence medium-term operating models if the pressure persists. For now, companies should treat it as a development that warrants close monitoring and practical preparation, rather than as a basis for sweeping conclusions.
Basis of this article and follow-up points
This article is based on the user-provided news title, event date, and event summary. No additional figures, company names, policy documents, or market data have been added beyond the provided information.
For developments of this kind, commonly relevant source types may include official announcements, company statements, industry association updates, authoritative media reporting, and trade or standards-related documents. A specific official source link was not provided in the input, so the underlying details still require ongoing verification.
Follow-up attention should focus on whether additional market participants adopt localized assembly or secondary inventory approaches, and whether customer requirements in Indonesia continue to shift toward Indonesian-language documentation, local response commitments, and DAP/DDP delivery structures.
The Archive Newsletter
Critical industrial intelligence delivered every Tuesday. Peer-reviewed summaries of the week's most impactful logistics and market shifts.