Training can lower manufacturing standards cost when it addresses measurable causes of defects, audit findings, and production delays. Financial approval should depend on demonstrated operational value.
Course fees reveal only part of the investment. Paid learning time, temporary production disruption, supervision, and competency verification also belong in the financial assessment.
The potential return extends beyond fewer rejected parts. Effective training can reduce troubleshooting hours, strengthen process consistency, and prevent recurring corrective actions after customer audits.
Across electronics, automotive, and other industrial sectors, targeted training helps teams apply relevant ISO, IATF, and IPC requirements more consistently within their specific production environments.
Drawing on GIM’s cross-sector benchmarking perspective, this article explains how financial approvers can evaluate training costs, measure credible savings, and prioritize investments with defensible returns.
What costs should financial approvers actually compare?
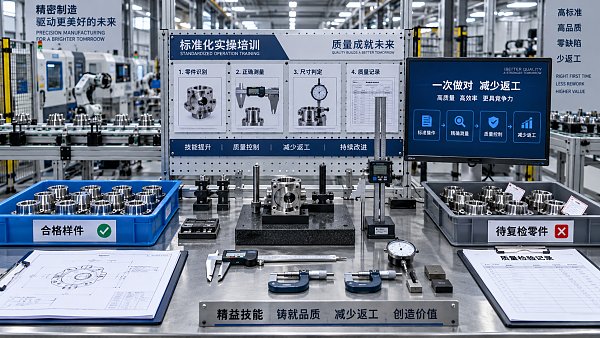
The relevant comparison is total cost before and after a defined training intervention. Comparing course prices alone misses the operational losses that training might prevent.
Separate standards-related spending into implementation, ongoing control, and failure costs. This makes it easier to identify which expenses workforce development can realistically influence directly.
Implementation costs include interpreting requirements, documenting processes, introducing inspection methods, and preparing personnel. Training may accelerate these activities, although some initial expenditure remains unavoidable.
Ongoing control costs include inspections, internal audits, calibration administration, recordkeeping, and competency maintenance. Better skills can reduce avoidable effort without weakening required controls or evidence.
Failure costs include scrap, rework, repeat testing, customer returns, expedited freight, and corrective action labor. These frequently provide the clearest starting point for financial analysis.
Some standards-related expenses are largely unaffected by training. Certification fees, necessary equipment upgrades, and mandatory external testing should remain separate unless a specific reduction is demonstrable.
Also distinguish cash savings from released capacity. Fewer rework hours create financial value, but they do not automatically reduce payroll or increase operating profit.
Capacity becomes monetizable when it reduces overtime, avoids hiring, or supports profitable additional output. Otherwise, report the improvement as available capacity with a stated utilization assumption.
Where does training produce the strongest financial return?
Training produces stronger returns when a costly failure has a clear competency component. Start with recurring losses and trace them to observable decisions or behaviors.
For electronics manufacturers, examples include inconsistent solder acceptance decisions, incorrect handling of moisture-sensitive components, and incomplete inspection records. Each can create avoidable rejection or repeat inspection.
In automotive supply chains, weak understanding of control plans, reaction plans, or measurement practices can allow process deviations to continue until containment becomes expensive downstream.
Precision tooling operations may benefit from instruction on measurement interpretation, setup verification, and tool wear recognition. Small improvements can matter when individual components carry substantial value.
Environmental infrastructure manufacturing may face losses from incorrect test execution or incomplete traceability. Training should target the applicable product specifications, procedures, and contractual acceptance criteria.
These examples identify investigation areas, not guaranteed savings. Confirm whether the underlying problem involves knowledge, equipment capability, unclear instructions, material variation, or unrealistic production targets.
If fixtures cannot hold tolerances, additional classroom instruction will not solve the constraint. Funding should address the technical cause, with training supporting the revised process.
Similarly, employees may understand a requirement but lack time to follow it. In that situation, staffing, scheduling, or process redesign deserves attention before further instruction.
Prioritize opportunities combining frequent failures, meaningful financial exposure, and a plausible skills gap. An expensive but extremely rare event may require a different risk-management approach.
How do ISO, IATF, and IPC requirements affect the training decision?
Financial approvers should first establish which requirements actually apply. A management system standard, an industry-specific requirement, and a product acceptance standard create different obligations and costs.
ISO 9001 addresses competence for work affecting quality management system performance. Organizations determine necessary competence, take appropriate action, evaluate effectiveness, and retain suitable documented evidence.
Training is one possible action; relevant education, experience, mentoring, or reassignment may also establish competence. Paying for a course does not itself demonstrate effective implementation.
IATF 16949 adds automotive-specific expectations, including provisions concerning training and competence. Applicable customer-specific requirements can introduce further obligations that affect training content and approval decisions.
IPC standards serve different purposes across electronics design, assembly, and acceptance. The relevant document, revision, product class, and customer contract determine what personnel must understand.
Do not assume every operator needs an external IPC credential. Verify whether certification is required contractually or whether documented internal qualification adequately meets the applicable expectations.
Conversely, replacing a required credential with informal instruction can create customer acceptance problems. Finance should confirm requirements with quality and commercial teams before approving substitutions.
GIM’s cross-sector benchmarking perspective helps structure comparisons, but requirements remain context-specific. A workforce budget should follow the site’s actual products, processes, customer commitments, and obligations.
What belongs in a complete training budget?
A realistic budget captures both visible spending and operational disruption. Underestimating either can make an otherwise useful program appear more profitable than it actually is.
Direct spending includes instructor fees, learning materials, assessment charges, travel, and any required credentials. Specify whether quoted prices cover all participants, assessments, and repeat attempts.
Employee participation also carries a cost. Include paid learning hours, supervisor involvement, temporary cover, and overtime where these create additional expenditure or consume constrained capacity.
Production disruption requires careful treatment. Use incremental lost contribution only when training prevents sales that cannot be recovered through rescheduling, inventory, or later available capacity.
Avoid counting the same interruption twice through wages and lost output. Finance should select a consistent costing method and explain how overlapping costs are handled.
Implementation may require updated work instructions, translated materials, practice assemblies, or revised inspection aids. These supporting investments often determine whether learning transfers into daily work.
Include follow-up observation and refresher training where justified by process changes or skill decay. A one-time event may be insufficient for complex or infrequent tasks.
Finally, distinguish mandatory competence spending from discretionary improvement investment. Both deserve cost control, but an essential requirement cannot be rejected solely because immediate payback appears limited.
How can you calculate a credible payback period?
Use a bounded pilot with an explicit baseline. Select one production area, define the targeted failure, and measure losses over a representative period before training.
Estimate benefits using avoidable costs, not headline revenue or broad claims about productivity. Scrap savings should reflect unrecoverable material and processing costs, net of recovery value.
The following illustration uses hypothetical figures for one manufacturing cell. It demonstrates an approval method; it is not an industry benchmark or a promised outcome.
Calculate simple payback as initial investment divided by monthly net benefit. Here, $24,000 divided by $3,000 produces eight months once the assumed improvement is established.
If benefits begin immediately and remain stable, first-year net benefit before the initial investment is $36,000. Subtracting $24,000 leaves a $12,000 surplus in this illustration.
First-year return on the initial investment would therefore be 50%. A slower ramp, lower production volume, or additional implementation costs would reduce that illustrative return.
Run a downside case before approval. At a 10% reduction, gross monthly benefit becomes $1,800; after ongoing costs, net benefit falls to $1,200 per month.
Payback then extends to 20 months after full benefits begin. This sensitivity makes the decision more useful than presenting a single optimistic estimate to management.
For larger or longer programs, assess discounted cash flows using company policy. Include timing, tax treatment where relevant, and whether benefits continue beyond the initial year.
How do you prove that training caused the improvement?
Attendance records establish participation, but they do not establish operational effectiveness. Verification should connect demonstrated competence with a measurable change in the targeted production outcome.
Before launch, define a small set of metrics: relevant defect rate, rework hours per unit, first-pass yield, or repeat findings associated with the trained task.
Normalize results for production volume and product mix. A lower scrap bill during a quiet month may reflect fewer units produced rather than better performance.
Record concurrent changes in materials, equipment, staffing, and inspection rules. Otherwise, savings from a new fixture or supplier improvement may be incorrectly attributed to training.
Where practical, compare similar trained and untrained groups, or stagger implementation across lines. Such comparisons strengthen attribution, although operational differences still require interpretation and documented judgment.
Assess practical competence through observed work, representative samples, or task-based evaluations. The assessment should resemble the actual decisions employees must make during normal production conditions.
Measure persistence after employees return to work. A short-lived improvement may indicate weak supervision, inaccessible instructions, or insufficient opportunities to practice the required skills consistently.
Assign joint ownership to operations, quality, and finance. Operations verifies feasibility, quality checks requirement coverage, and finance validates whether reported benefits translate into economic value.
What should a financial approver require before releasing funds?
A strong proposal identifies the applicable requirement, the current competency gap, the affected process, and the financial loss. Each element should have a named owner.
It should explain why training addresses the cause and whether alternatives were evaluated. Better instructions, process automation, or equipment repair may offer a stronger return.
Require a complete budget, conservative benefit assumptions, and a measurement plan. Specify which benefits represent cash savings, usable capacity, or reduced exposure to uncertain future losses.
Risk reduction deserves separate consideration when consequences are severe. Estimate exposure using credible scenarios, while avoiding unsupported probabilities or counting the same loss across multiple categories.
Avoid treating a passed audit as proof of financial return. Audit outcomes matter, but the business case should also examine recurring losses and sustained process performance.
Release funding in stages when uncertainty is material: establish the baseline, run the pilot, verify results, and expand where evidence supports the remaining investment decision.
Approve broader deployment when requirements are covered, competence is demonstrated, and benefits survive conservative assumptions. Revise programs whose results depend on unrealistic attribution or utilization expectations.
Training makes manufacturing standards cost more manageable when it improves specific work and prevents measurable losses. The strongest investment decisions connect required competence, operational evidence, and financial outcomes.